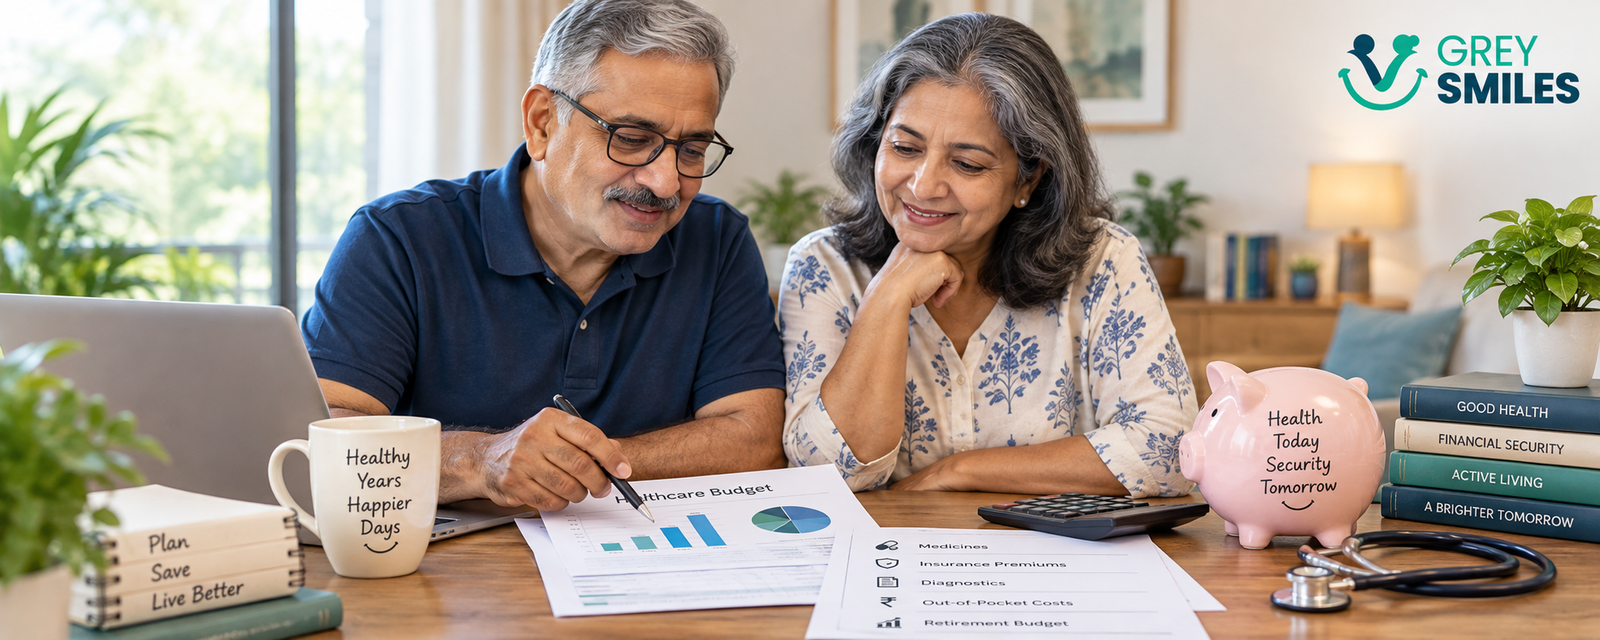
Healthcare is one of the retirement expenses that is easy to underestimate. While you may know what you spend on medicines, consultations or insurance today, those costs can change as your retirement progresses.
Healthcare budgeting is therefore not about predicting every medical expense. It is about making healthcare a visible part of your retirement budget, rather than treating it as an unexpected expense whenever it arises.
At a Glance
- Start with what you spend today. Your current healthcare spending provides a useful starting point for your retirement budget.
- Separate regular and unexpected costs. Medicines and consultations are different from hospitalisation, rehabilitation or other irregular expenses.
- Insurance is only one part of the picture. Premiums, exclusions, co-payments and expenses outside the policy also affect your budget.
- Allow for changing costs. Healthcare spending can change as both prices and your own healthcare needs change.
- Review the budget periodically. Your healthcare budget should evolve as your retirement and health circumstances change.
What Does Healthcare Budgeting Mean in Retirement?
Healthcare budgeting means giving healthcare its own place within your retirement spending plan.
That includes the costs you can reasonably anticipate, such as medicines, consultations, diagnostics and insurance premiums, as well as a plan for expenses that may not occur every year.
The objective is not to create a perfect estimate. It is to make sure that healthcare is visible when you work out how much your retirement may cost.
Start With Your Current Healthcare Spending
A useful first step is to look at what your household actually spends on healthcare today.
| Healthcare cost | What to look at |
|---|---|
| Medicines | Regular prescriptions and other recurring medicines |
| Consultations | Doctor visits and specialist consultations |
| Diagnostics | Tests, scans and other investigations |
| Dental and vision | Expenses that may not always form part of your health insurance coverage |
| Insurance | Current and expected health insurance premiums |
Do not assume that today’s healthcare spending will remain unchanged throughout retirement. It is a starting point for understanding the scale of the expense, not a prediction of what you will eventually spend.
Regular Healthcare Costs and Unexpected Expenses
One reason healthcare can be difficult to budget is that not every expense arrives regularly.
Your monthly medicines may be predictable. A hospitalisation, procedure, rehabilitation requirement or period of home healthcare may not be.
This is where your retirement plan needs to distinguish between the healthcare costs you expect to pay as part of normal spending and the accessible money you may want available for less predictable expenses.
A separate healthcare reserve can serve this second purpose. For a closer look at that question, see How Much Should You Keep Aside for Healthcare in Retirement?
Do Not Forget Health Insurance Premiums
Health insurance can reduce the financial impact of some medical events, but the insurance premium itself is a retirement expense.
If you are still working, an employer may currently provide some or all of your health insurance. That can change when you retire.
Before retirement, understand what happens to employer-sponsored cover and what you may need to pay for your own protection. Our guide What Happens to My Health Insurance When I Retire? looks specifically at this transition.
You should also understand what your existing policy actually covers, including co-payments, deductibles, exclusions, waiting periods and other limits. Is My Health Insurance Enough for Retirement? looks at the question of insurance adequacy in more detail.
Healthcare Costs Can Change Over Time
Your current annual healthcare spending is only a starting point because both healthcare prices and your own needs can change.
Retirement may last for many years. Medicines, consultations, diagnostics and treatment costs may not remain at today’s levels, while your healthcare requirements may also change with age.
This does not mean you need to predict the exact rate at which every healthcare expense will rise. The more useful approach is to recognise that today’s healthcare budget may not be enough several years from now.
GREYSMILES CALCULATOR
Health Inflation Planner
If you know roughly what you spend on healthcare today, the GreySmiles Health Inflation Planner can help you explore how that expense could change over your planning horizon under different inflation assumptions.
It is a planning exercise, not a prediction of your actual future medical bills.
Healthcare Is More Than Hospitalisation
When people think about retirement healthcare, hospitalisation is often the first expense that comes to mind. Your regular healthcare budget can be broader than that.
Medicines, consultations, diagnostics, dental care, vision care, rehabilitation and home healthcare can all affect your retirement spending.
Some of these expenses may be covered only partly, or not covered at all, by your insurance. That is why healthcare budgeting should consider both insured and self-funded costs.
Our broader guide, How to Plan for Healthcare Costs in Retirement, brings these different elements together.
How Should Couples Think About Healthcare Budgeting?
A household healthcare budget should not automatically assume that both spouses will have identical needs.
One spouse may have higher regular medical expenses, a different insurance arrangement or different healthcare needs. Employer coverage may also apply differently to each person after retirement.
Review the household as a whole, but understand the healthcare position of each person separately.
Bring Healthcare Into Your Retirement Numbers
Once you have estimated your regular healthcare spending, insurance premiums and the accessible reserve you may want for unexpected expenses, bring these numbers into your wider retirement budget.
This matters because healthcare is not an isolated financial decision. A higher healthcare budget affects the amount of income you need during retirement and may also affect the retirement corpus you are trying to build.
The aim is not to inflate your retirement target simply because healthcare is uncertain. It is to make sure that a significant category of future spending has not been left out.
GreySmiles Take
Healthcare should not be treated as an occasional retirement emergency. Give it a place in your regular retirement budget, understand what insurance is likely to cover, keep accessible money for costs that remain outside insurance and revisit the numbers as your circumstances change.
A Simple Annual Healthcare Budget Review
You do not need to rebuild your healthcare budget every month. An annual review can help keep the assumptions realistic.
- What did we actually spend on healthcare during the past year?
- Have regular medicines or consultations changed?
- Have health insurance premiums changed?
- Has our insurance coverage or policy structure changed?
- Are there healthcare costs that we are now paying ourselves?
- Is our accessible healthcare reserve still appropriate for our circumstances?
- Have our retirement income or spending assumptions changed?
The purpose of the review is not to predict every medical event. It is to make sure your retirement plan continues to reflect the healthcare costs you are actually facing.
Healthcare Budgeting Checklist
- Record current annual healthcare spending.
- Separate regular healthcare costs from less predictable expenses.
- Include health insurance premiums in your retirement budget.
- Review what your insurance may not cover.
- Consider how healthcare costs could change over time.
- Keep accessible money available for appropriate out-of-pocket expenses.
- Bring the resulting healthcare budget into your wider retirement calculations.
- Review the assumptions periodically.
FAQs
Why should healthcare have a separate place in a retirement budget?
Healthcare can include both regular expenses and unpredictable costs. Giving it a separate place in the retirement budget makes it easier to see what you may need to fund rather than treating medical expenses as an afterthought.
Does health insurance remove the need to budget for healthcare?
No. Insurance can provide an important layer of protection, but premiums, co-payments, deductibles, exclusions and expenses outside the policy may still need to be funded.
How should I estimate future healthcare costs?
Start with your current spending and consider how healthcare prices and your own needs may change over time. The GreySmiles Health Inflation Planner can be used as an illustrative planning exercise.
Should healthcare be included when calculating my retirement corpus?
Yes. Healthcare is one of the spending categories that can affect the amount of income and savings you may need during retirement.
Is there a fixed amount everyone should budget for healthcare after retirement?
No. Healthcare needs vary by individual, age, health, insurance coverage, family circumstances and other factors. A useful budget should start with your own situation rather than a universal number.
Bottom Line
Healthcare budgeting for retirement is less about finding one perfect number and more about making the expense visible.
Start with what you spend today. Add insurance premiums, recognise the costs that may remain outside insurance, allow for changing healthcare needs and bring the resulting estimate into your wider retirement plan.
A retirement plan becomes more useful when it reflects the expenses you are actually likely to face, including healthcare.
Sources & References
For current health insurance rules and regulatory information, refer to the Insurance Regulatory and Development Authority of India (IRDAI).
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.